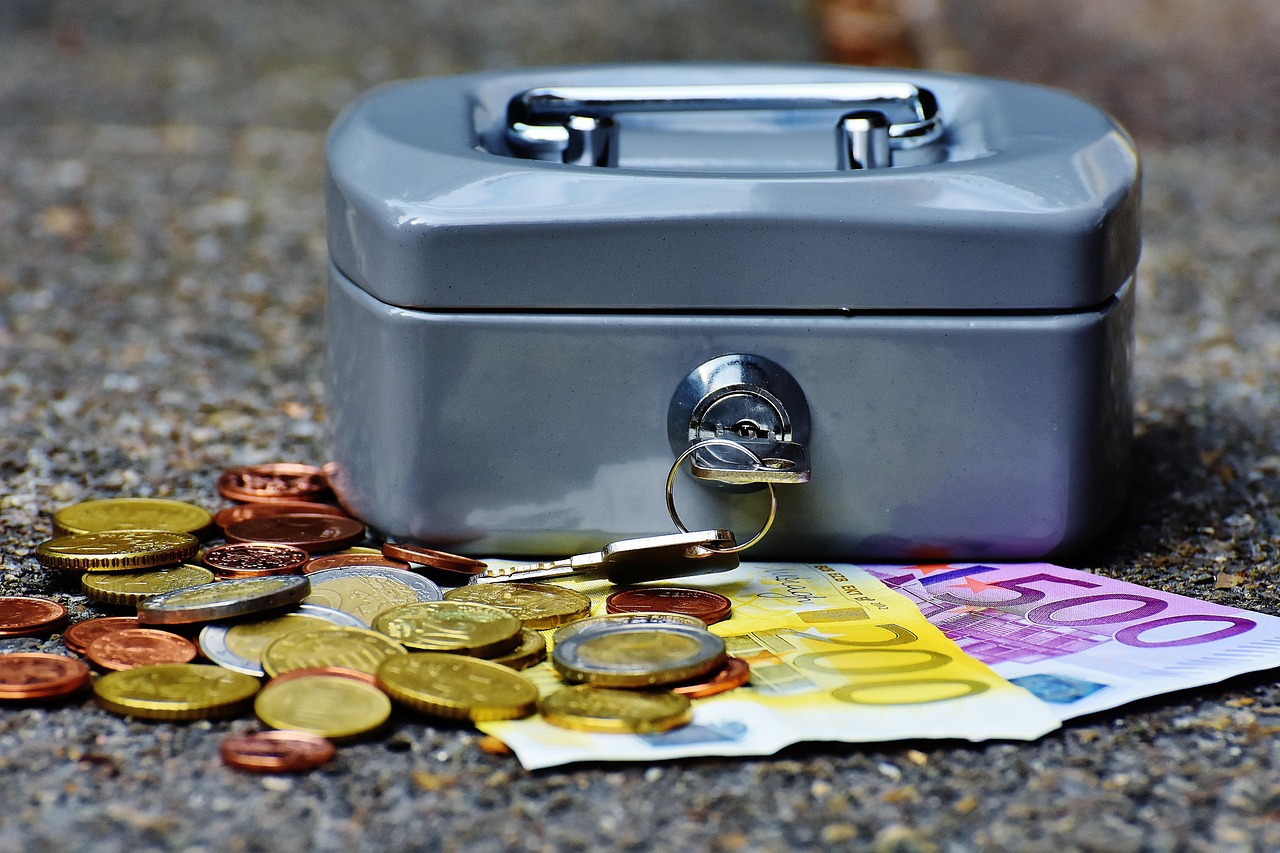
Life is inherently unpredictable. Whether it is an unexpected car repair, a sudden medical bill, or an unforeseen period of unemployment, financial shocks can derail even the most carefully crafted budget. An emergency fund acts as your personal financial safety net, providing the peace of mind necessary to navigate life’s hurdles without resorting to high-interest debt. Building this reserve is not just a suggestion; it is the cornerstone of a healthy financial foundation.
Understanding the Role of an Emergency Fund
Why You Need a Financial Cushion
An emergency fund is a dedicated pool of money set aside specifically for urgent, unexpected expenses. Unlike savings for a vacation or a new home, this money is intended solely for survival during financial volatility. Without this buffer, many people are forced to use credit cards or take out predatory loans, which can lead to a cycle of debt that is difficult to escape.
The Psychological Benefits of Savings
Beyond the math, there is a profound psychological benefit to having liquidity. Research consistently shows that individuals with at least $1,000 in savings report significantly lower levels of financial stress. Knowing that you can cover an emergency without panic allows you to make better, long-term financial decisions rather than reactive ones.
Determining Your Target Savings Goal
The Three-to-Six Month Rule
The standard recommendation from financial experts is to save between three and six months of essential living expenses. Essential expenses include:
- Housing costs (rent or mortgage)
- Utilities (electricity, water, heat)
- Groceries and household essentials
- Insurance premiums
- Minimum debt payments
Factors Influencing Your Target
Your specific target depends on your lifestyle. Consider these factors when setting your goal:
- Job stability: If you are a freelancer or work in a volatile industry, aim for the higher end (6-9 months).
- Dependents: If you have children or elderly parents relying on you, a larger buffer is necessary.
- Health: If you have ongoing medical needs, ensure your fund accounts for potential out-of-pocket maximums.
Where to Keep Your Emergency Fund
Liquidity and Accessibility
The primary purpose of an emergency fund is immediate access. You should never invest this money in volatile assets like individual stocks or cryptocurrency where the value could drop right when you need to withdraw it. Your funds should be liquid and stable.
The Best Accounts for Emergency Savings
- High-Yield Savings Accounts (HYSA): These offer competitive interest rates while keeping your money FDIC-insured and easily accessible via transfers.
- Money Market Accounts: These often come with check-writing capabilities or debit cards, providing slightly more convenience.
- Traditional Savings Accounts: While they offer lower interest, they are perfectly safe and readily available at your local bank.
Strategies for Building Your Fund Quickly
Automate Your Savings
The most effective way to build wealth is to “pay yourself first.” Set up an automatic transfer from your checking account to your savings account immediately after receiving your paycheck. By treating this as a non-negotiable bill, you ensure consistency.
Small Steps to Big Gains
If saving three months of expenses feels daunting, start with a “starter emergency fund” of $1,000. Once you hit that milestone, you can aggressively tackle high-interest debt or increase your savings contributions. Consider these tactical ways to boost your balance:
- Direct a portion of your tax refund or annual bonus straight into the account.
- Sell unused household items through online marketplaces.
- Reduce discretionary spending (e.g., dining out or streaming subscriptions) for a set period.
When to Use Your Emergency Fund
Defining a True Emergency
One of the biggest pitfalls is “lifestyle creep” or using the fund for non-emergencies. To maintain the integrity of your safety net, reserve the funds only for events that are:
- Unexpected: You did not know it was coming.
- Necessary: You cannot live without fixing the problem.
- Urgent: It needs to be handled immediately.
Examples of Appropriate Usage
Use your emergency fund for instances like job loss, emergency home repairs (e.g., a burst pipe), urgent medical bills, or sudden travel for family crises. Do not use the fund for vacations, holiday gifts, or minor inconveniences.
Conclusion
Building an emergency fund is a marathon, not a sprint. It requires discipline, consistency, and a clear understanding of your financial needs. By establishing a liquid reserve, you are not just saving money; you are buying freedom from the stress that accompanies life’s inevitable surprises. Start by calculating your essential monthly expenses, choose a high-yield account, and automate your contributions today. Even small, consistent efforts will pay off significantly, providing you with the security and confidence to pursue your long-term financial goals.